stop making your landlord rich
We've helped over 2,800 families purchase a home and start building wealth
Get your mortgage pre-approval today. No hard credit pull. No impact on your credit score.
With 20+ years of experience and in-house loan programs for every scenario, we'll help you become a homeowner.
See What You Qualify For!
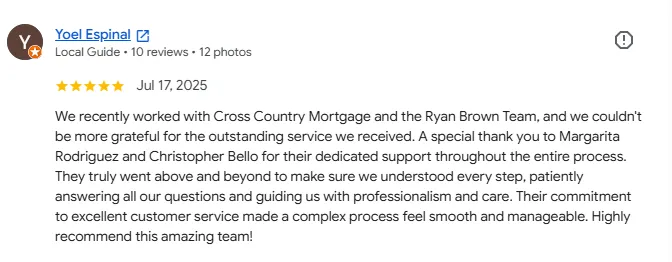
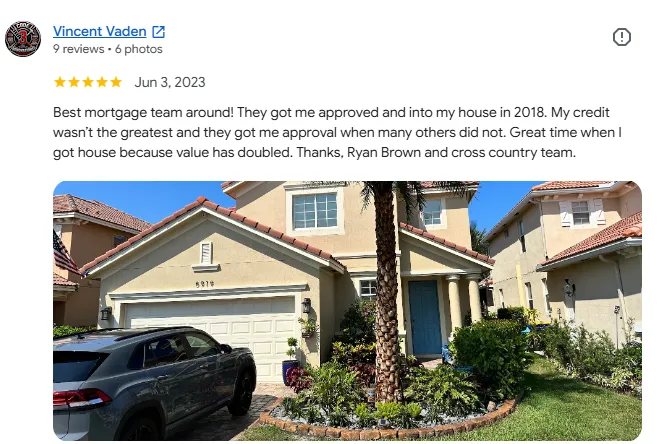
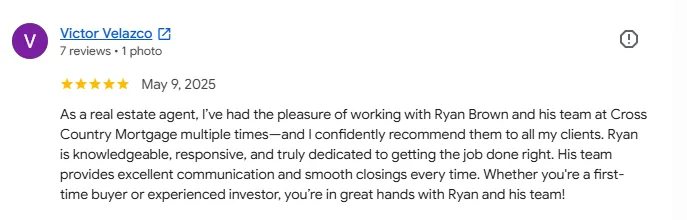
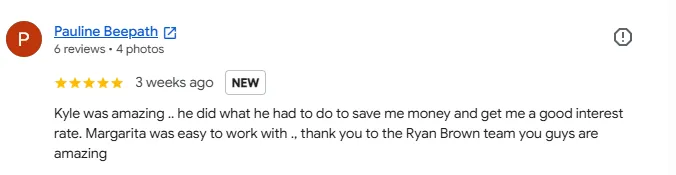
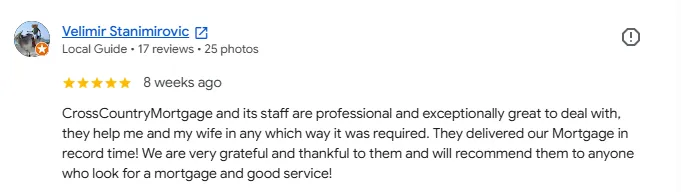
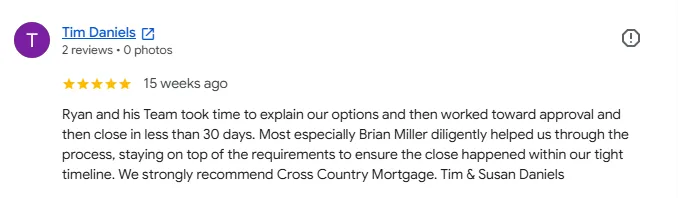
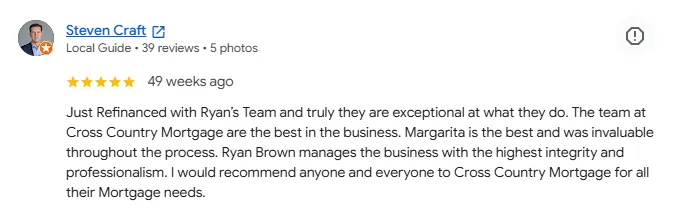
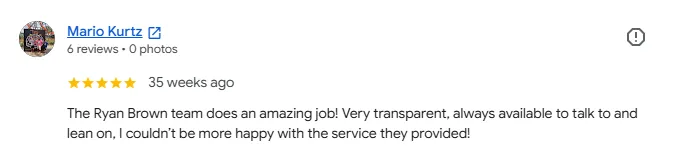
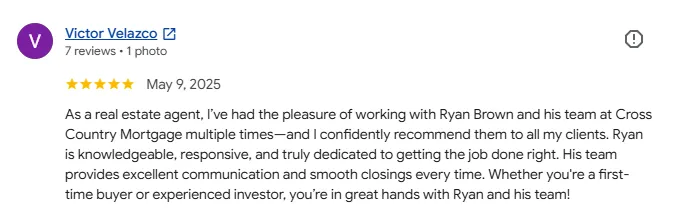
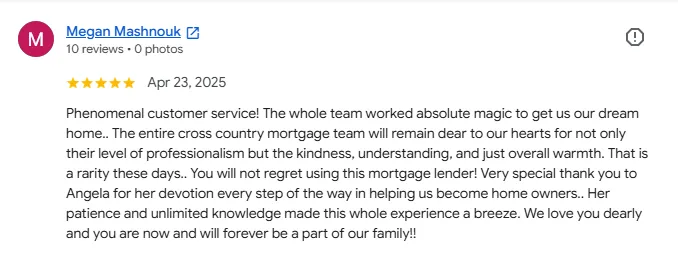
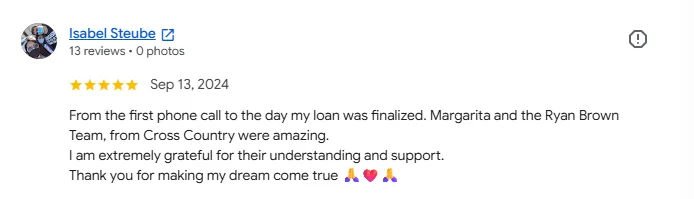
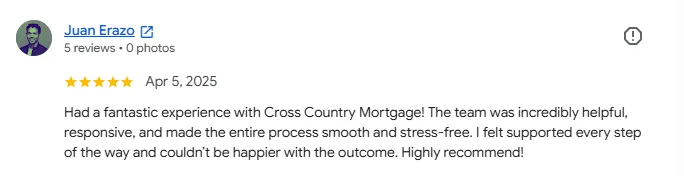
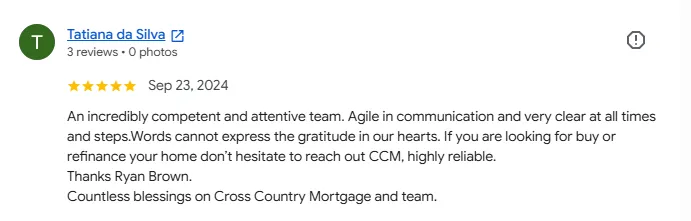
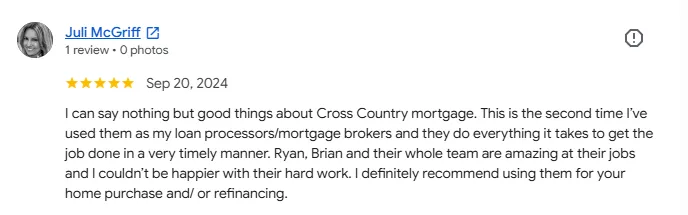
our reputation speaks for itself
Voted #1 Mortgage Lender
in Palm Beach County and Treasure Coast (by Palm Beach Post & TC Palm)
Still have some questions...?
Frequently Asked Questions
What have our clients asked us?
Question 1: What is the difference between a pre-qualification and a pre-approval?
A pre-qualification is issued when the mortgage lender does not review/verify any financial documentation (income, credit, asset, and liability). A pre-approval is issued when the mortgage lender verifies all financial documentation provided (income, credit, assets, and liabilities).
Question 2: What documents do I need to get pre-approved?
To get pre-approved, you'll typically need your last two pay stubs, two years of W-2s and tax returns, two months of bank statements, and a valid government-issued ID. If you're self-employed, we'll usually look at your full business tax returns as well. Every situation is a little different, so my team and I will let you know exactly what's needed upfront.
Question 3: What loan types do you offer?
We offer Conventional, FHA, VA, USA, Jumbo, Bank Statement, Investor Loans, and dozens of specialized in-house loan products to meet every residential scenario.
Question 4: How long does it take to get a pre-approved?
Our team can issue out a same-day pre-approval in most cases. As soon as we receive all of your relevant documents, we have our approval team review and issue out the approval directly to you.
Question 5: Will getting pre-approved hurt my credit score?
Absolutely not! When issuing a mortgage pre-approval we only do a soft-check on your credit report. This means there is no hard inquiry on your report, and no impact on your credit score.
Question 6: How long is my pre-approval valid for?
Mortgage pre-approvals are usually valid for 60-90 days. After the initial approval, we only need updated documents to issue out an updated pre-approval.
Question 7: What credit score do I need to buy a home?
It depends on the loan program. Conventional loans typically require a 620 or higher, FHA goes as low as 580 (and sometimes 500 with a larger down payment), and VA loans are flexible as well. If your score isn't where it needs to be, my team can help you build a plan to get there.
Question 8: How much do I need for a down payment?
Less than most people think. FHA loans start at 3.5% down, Conventional can go as low as 3%, VA and USDA loans offer zero-down options for those who qualify. We'll match you with the program that fits your situation.
Question 9: What are closing costs, and how much should I expect to pay?
Closing costs cover things like the appraisal, title insurance, lender fees, and prepaid items like taxes and insurance. In Florida, you're typically looking at 2–5% of the purchase price. We break all of this down for you upfront so there are no surprises at the closing table.
Question 10: Can I get pre-approved if I'm self-employed?
Absolutely. We work with self-employed borrowers every day. The documentation looks a little different — we'll use your business tax returns and may look at bank statements to verify income — but we have loan programs specifically designed for entrepreneurs and business owners.
Question 11: Can I use gift funds for my down payment?
Yes, most loan programs allow gift funds from a family member. We just need a signed gift letter confirming it's a gift and not a loan, along with documentation showing the transfer. There are some guidelines depending on the program, but my team will walk you through exactly what's needed.
Question 12: What is PMI, and how do I avoid it?
PMI — private mortgage insurance — is a monthly charge added when you put less than 20% down on a Conventional loan. It protects the lender, not you. The good news is it's not forever; once you reach 20% equity, it can be removed. FHA loans have their own version called MIP, and VA loans don't require it at all. We'll help you weigh whether a smaller down payment now is worth the short-term cost.
Question 13: Can I buy a home if I have student loan debt?
Yes. Student loans don't disqualify you — it's about your overall debt-to-income ratio. We look at your monthly payment obligations relative to your income, and there are specific guidelines for how different loan programs calculate student debt. Plenty of my clients carry student loans and still qualify comfortably.
Question 14: Can I buy a home if I recently changed jobs?
In most cases, yes. Lenders like to see a two-year employment history, but that doesn't mean two years at the same company. If you moved into a similar role or advanced in your career, that typically works fine. We'll just need to document the transition and verify your current income.
Question 15: How much house can I afford?
That depends on a few factors — your income, your monthly debts, your down payment, and the interest rate you qualify for. A good rule of thumb is that your total monthly housing payment (mortgage, taxes, insurance) shouldn't exceed about 28–33% of your gross monthly income, but every situation is different. The best way to get a real number is to get pre-approved — my team and I will run everything and give you a clear picture of what you can comfortably afford.
The Homebuying Journey

Find Out Where You Stand
We review your income, credit, and overall financial picture so you know exactly what you qualify for. No guessing or surprises!
Get Matched With The Right Loan Program
Homebuyers have more options that they realizes - FHA, Conventional, VA, down payment assistance. We find the right program for you!
Get Pre-Approved
A pre-approval letter tells sellers and agents you're a serious, qualified buyer. It gives you the confidence to shop and the credibility to compete.
We Guide You Through The Process
Once you're under contract, our team handles the heavy lifting — collecting documents, coordinating with title and your agent, and ensuring nothing falls through the cracks for closing
Stay Informed Every Step of The Way
You'll never wonder what's going on. We communicate clearly and proactively so you always know where things stand between contract and closing
We Get You To
Closing Table
You sign, you get the keys, and you're a homeowner. And after closing, we're still here — for questions, future refinances, or the next time you're ready to buy.
THE RYAN BROWN TEAM
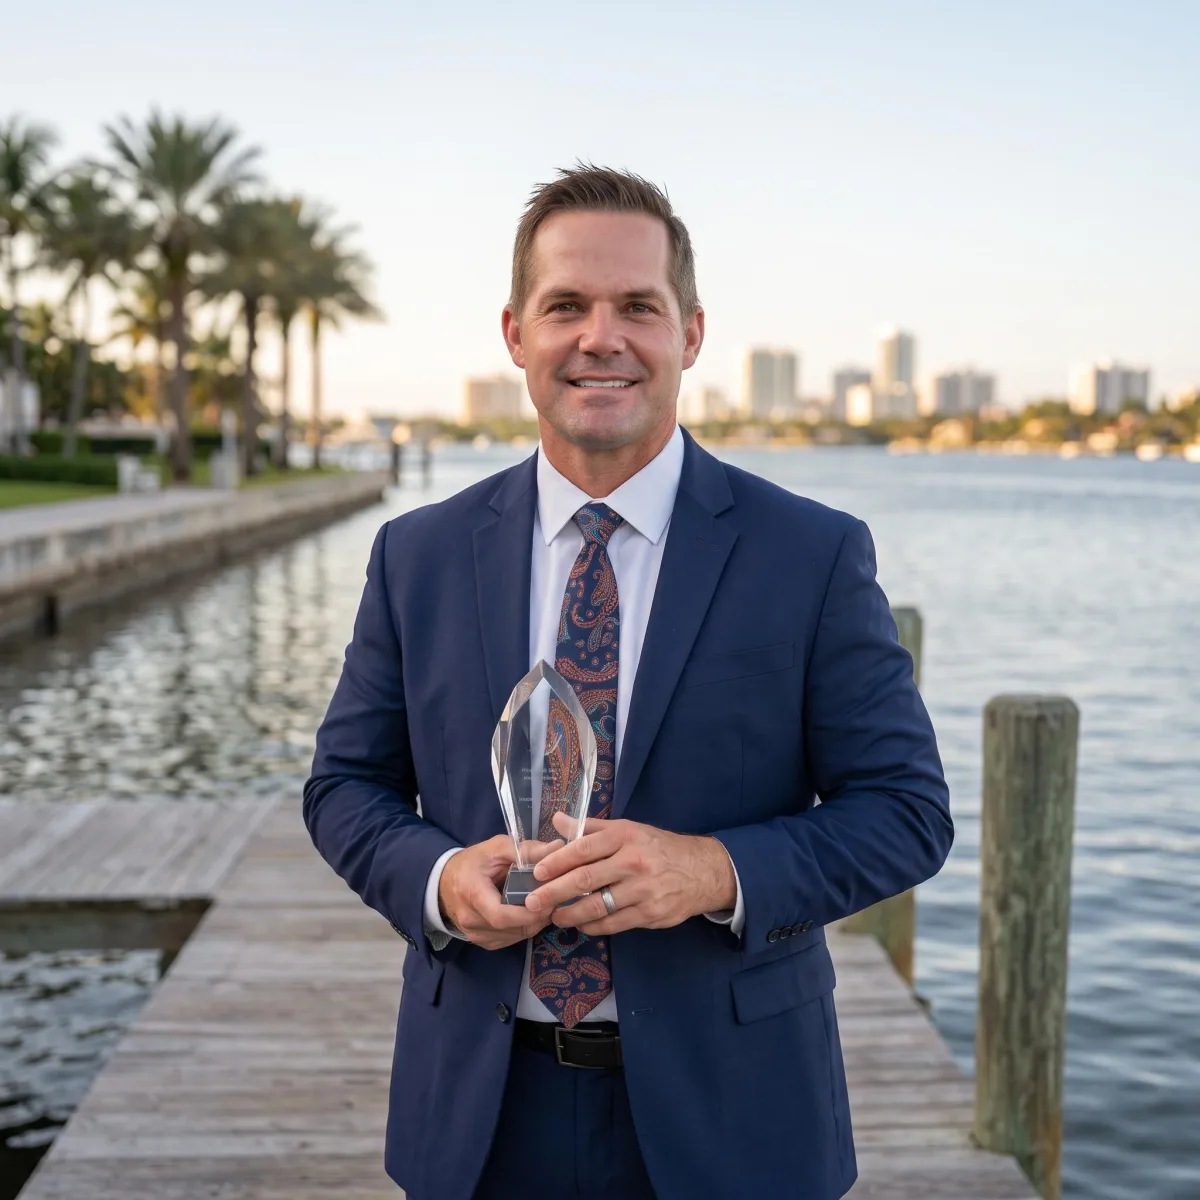
Hey, I'm Ryan!
I help families build wealth through real estate, as a mortgage loan originator. My goal is to help the homebuying process be as easy and stress-free as humanly possible.
I have helped over 2,800 families purchase homes and start their wealth creation journey.
Top 1% Loan Originator in USA
Voted #1 Mortgage Lender in Palm Beach & Treasure Coast
Over 25 years experience